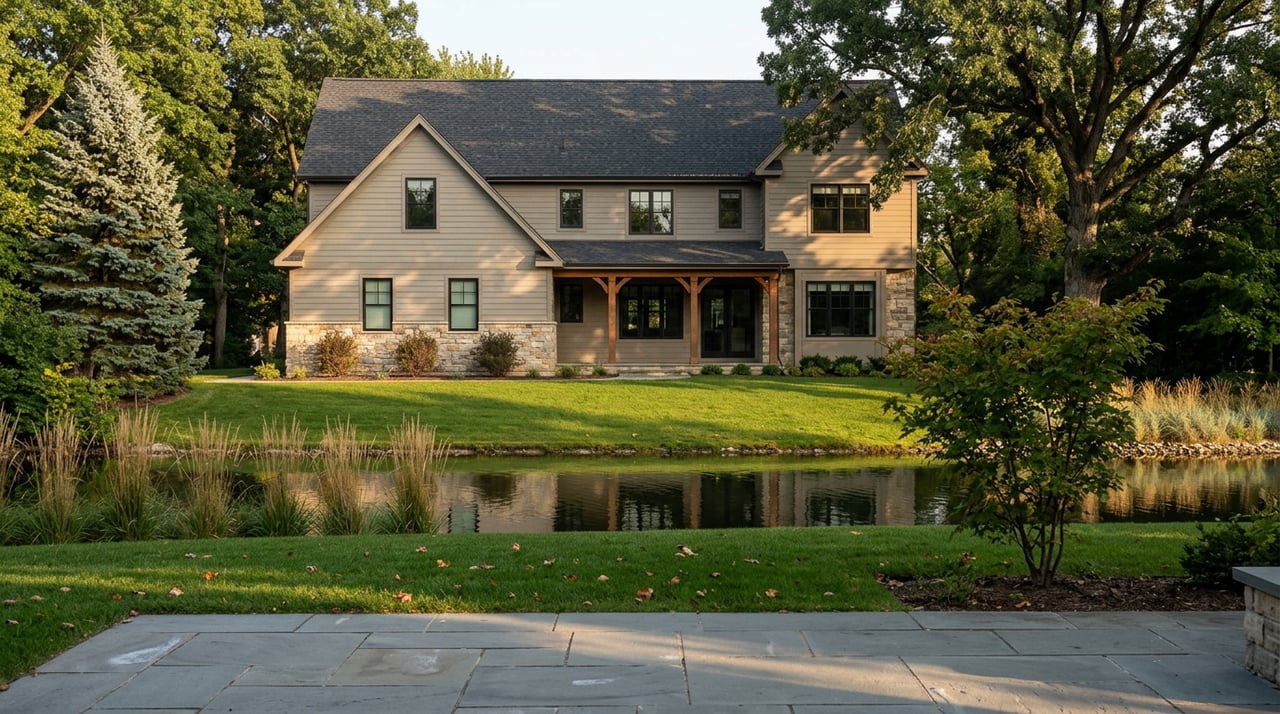
Why Loveland's Median Home Price Skips Right Past Boyd Lake
September 17, 2026
September 17, 2026
Ask two different agents what a home costs near Boyd Lake and you can get two answers that are both true.
That gap is the part Loveland's citywide median never mentions, and it's worth understanding before you fall in love with a listing photo.
Depending on which aggregator you check and which month you catch it, Loveland's citywide median has landed anywhere from about $490,000 to $550,000 across various points in 2026. Redfin put the median sale price at $490,000 over the three months ending in April 2026, up 1 percent year over year, with homes averaging 59 days on market. Zillow's home value index, updated through July 2026, showed the average home value sitting closer to $502,000 to $510,000, down about 1 percent over the past year. By August 2026, Movoto's snapshot of closed sales showed a median of $550,000.
None of those numbers is wrong. They're measuring slightly different things in slightly different windows, which is normal for a market that's cooled from its 2021 to 2022 pace but hasn't collapsed. What none of them can tell you is where in Loveland that price actually lives.
Realtor.com's neighborhood-level data, compiled through a first-time buyer guide to the area, tells a different story. Mariana Butte carries a median around $827,500. Southeast Loveland sits near $773,250. Rural Southwest Loveland runs closer to $979,000. Those three pockets alone sit well above the citywide figure.
At the other end, East Central and West Central Loveland, along with some downtown and Centerra attached product, cluster in the entry-level band, with Centerra townhome and condo collections starting in the $300,000s and Van de Water's median listing price closer to $554,500. A single-family home in some Centerra collections starts in the $600,000s.
So when someone tells you Loveland's median is $490,000 or $550,000, the honest response is: which Loveland?
Say you've done that work. You've decided the Boyd Lake corridor is where you want to be, drawn by the water, the trail access, and the proximity to both Fort Collins and Denver. You're now comparing two listings in roughly the same price band, maybe $700,000 to $800,000, both marketed as lake-adjacent.
Here's where the second, quieter cost variable shows up. The City of Loveland maintains an official list of active metropolitan districts, and one of them is literally named Waterfront.
This isn't unique to Boyd Lake. It's how growth has been financed across Loveland's newer development for close to a decade. The city's Title 20 ordinance, adopted in 2024, now requires an 18-point review of every metro district service plan before City Council approves it, specifically to standardize how debt, mill levy caps, and transparency requirements get disclosed to buyers. The state's own guidance puts it plainly: these districts exist so that the people who move into new development pay for its infrastructure, rather than spreading that cost across everyone else in town.
According to the Loveland Midtown Metropolitan District FAQ, Colorado calculates property tax with a formula that's public record: actual value times the residential assessment ratio times the mill levy, divided by 1,000. As of the most recent published guidance from Kinston Metro District, that assessment ratio sits at 7.15 percent.
Here's how that plays out on a $750,000 home, a price point that lands comfortably inside both the Waterfront and Mariana Butte range.
| Scenario | Mill levy used | Assessed value (7.15%) | Illustrative annual district tax | Monthly equivalent |
|---|---|---|---|---|
| No metro district | 0 | $53,625 | $0 | $0 |
| Published cap from Lakes at Centerra Consolidated Metro District | up to 70 mills | $53,625 | ~$3,754 | ~$313 |
| Kinston Metro District, published service-plan cap | up to 77 mills | $53,625 | ~$4,129 | ~$344 |
Those are illustrations built from each district's own published mill levy cap, not a live tax bill for any specific address. Actual current levies move year to year and can sit below the cap. But the range lines up with what buyer-facing guides in the area have separately estimated, that a metro district can add somewhere between $150 and $400 or more to a monthly housing payment. The point isn't the exact dollar. It's that this line item exists in some Loveland neighborhoods and doesn't exist in others, and it doesn't show up in a Zestimate.
Worth knowing too: Loveland's metro district landscape isn't static. Voters inside the Lakes at Centerra district went to the polls on November 4, 2025, and approved consolidating what had been three separate metropolitan districts, Nos. 1, 2, and 3, into a single Lakes at Centerra Consolidated Metropolitan District. If you're comparing an older listing sheet to a current one in that community, the district structure itself may have changed since it was written.
None of this is a reason to avoid a neighborhood. Metro districts fund real infrastructure, roads, water lines, parks, and in some cases the trails and open space that make lake-adjacent living appealing in the first place. The goal is simply to know which cost structure you're signing up for before the offer goes in, not after the first tax bill arrives.
Can a mill levy go up after I move in? The specifics vary by district, which is exactly why the service plan is worth requesting.
Is a home with no metro district automatically the better deal? Not necessarily. It depends on lot size, age of infrastructure, HOA coverage, and what amenities the district-funded community includes that the older parcel doesn't. The comparison only works once you've priced both sides of the ledger.
If you're weighing a Boyd Lake listing against a Centerra one, or trying to figure out why two homes at the same price feel like they cost different amounts to own, that's exactly the kind of comparison worth working through with someone who knows which district sits under which street. Catherine Montgomery and the Power of 3 team can pull the current mill levy, the HOA structure, and the comparable sales side by side before you write an offer. Start Your Home Search today.
This article is general information, not legal, tax or financial advice. Consult a qualified professional about your situation.
October 29, 2026
October 22, 2026
October 15, 2026
October 8, 2026
October 1, 2026
September 24, 2026
September 17, 2026

September 10, 2026
September 3, 2026
Known for my approachable, professional style, I combine strong negotiation skills with modern marketing and technology to help clients achieve their real estate goals.
Catherine Montgomery
PO BOX: 270005 Fort Collins, CO 80527